Oceanfront vs. Lakefront vs. Riverfront: Which Waterfront Lifestyle is Right for You?
The dream of living by the water is a powerful one. It’s the sound of waves crashing on the shore as you sip your morning coffee, the profound calm of a glass-still lake at dawn, or the gentle, persistent flow of a river winding past your backyard. While this dream is universal, the reality of each waterfront type is vastly different. Choosing the right one is about much more than just the view; it’s about choosing a lifestyle.
Here at homes-in-riverside.com, we are experts in turning waterfront dreams into reality. We understand that the perfect property isn’t just about the house; it’s about the lifestyle that comes with it, and we specialize in providing clear, authoritative information about waterfront properties. This guide is designed to help you navigate the unique characteristics of oceanfront, lakefront, and riverfront living to find the perfect match for you.
In this article, we’ll break down the key differences in lifestyle, costs, maintenance, and activities to help you decide which shore is calling your name.
Key Takeaways
Oceanfront: Best for those who love the beach, saltwater activities, and dramatic views, but be prepared for higher costs, public access, and rigorous maintenance due to salt and storms.
Lakefront: Ideal for families and those seeking a strong sense of community, freshwater sports, and four-season recreation. Water levels can fluctuate, and some lakes have seasonal accessibility.
Riverfront: Offers a unique blend of tranquility and dynamic scenery, with opportunities for boating and fishing. Buyers must consider flood risks, water currents, and potential bank erosion.
The Right Choice: Your ideal waterfront lifestyle depends on your priorities regarding recreation, privacy, budget, and tolerance for maintenance and environmental risks.
TL;DR
Choosing a waterfront home means picking a lifestyle, not just a location. Oceanfront living offers expansive views and beach culture at a premium price with high upkeep. Lakefront living provides a calmer, community-oriented experience centered on freshwater fun. Riverfront homes deliver dynamic, ever-changing scenery and direct boating access, but require careful consideration of flood zones and currents.
A Quick Comparison: Ocean vs. Lake vs. River at a Glance
Oceanfront living offers dramatic views and beach access but comes with higher costs and maintenance.
The allure of the ocean is undeniable, promising the rhythm of the tides and endless horizons. This lifestyle is perfect for those who crave the energy of the coast and are prepared for the unique responsibilities that come with it. The decision to buy an oceanfront home is an investment in a specific way of life, one that is deeply connected to the power and beauty of the sea.
The Pros of Living on the Ocean
Unmatched Scenery and Beach Access: The primary draw is, of course, the view. Waking up to panoramic sunrises or sunsets over the water is a daily luxury. Direct access to sandy beaches means your backyard is a playground for swimming, sunbathing, and building sandcastles. This constant connection to the water is one of the key benefits of waterside living.
Active, Outdoor Lifestyle: The ocean encourages a lifestyle filled with activity. From surfing and paddleboarding to beach volleyball and long walks on the sand, there are endless opportunities to stay active. Coastal communities, like those in Florida, often have vibrant social scenes centered around beach life.
Strong Investment Potential: Desirable oceanfront homes are a finite resource, which often helps them hold their value and appreciate over time. Their appeal to vacationers also creates high potential for lucrative rental income, turning your dream home into a smart financial asset.
The Cons of Living on the Ocean
The Battle Against the Elements: Saltwater air is relentless and highly corrosive. It can cause metal to rust, wood to rot, and paint to peel at an accelerated rate. This means constant upkeep for everything from your HVAC unit and window frames to your car and outdoor grill.
Higher Costs and Insurance: The premium for an ocean view is significant. These properties command top dollar and come with higher property taxes. Furthermore, homeowners insurance is substantially more expensive. According to the Insurance Information Institute, you will almost certainly need separate, mandatory flood insurance through the National Flood Insurance Program (NFIP) and may need additional windstorm coverage, all of which can add thousands to your annual expenses. Finding ways to lower your homeowner’s insurance becomes a top priority.
Storms and Erosion: Homes on the coast are on the front lines for hurricanes, nor’easters, and tropical storms. Storm surge is a major threat, and long-term coastal erosion can gradually eat away at your property, potentially threatening your home’s foundation. The Federal Emergency Management Agency (FEMA) provides extensive resources on coastal construction and flood risks that are essential reading for any prospective buyer.
Privacy and Tourists: Your slice of paradise may not be entirely private. Many beaches are public, meaning you’ll share your backyard with tourists and locals, especially during peak seasons. This can lead to issues with noise, foot traffic, and a general lack of seclusion.
Lakefront properties provide a serene, community-focused lifestyle centered on freshwater recreation.
A lakefront home is the quintessential escape, offering a peaceful retreat and a close-knit community vibe. It’s a versatile choice that can serve as a year-round residence in a place like Granbury, TX, or a seasonal getaway for the whole family. The process of buying a waterfront lake home often focuses on finding a place where memories can be made.
The Pros of Living on a Lake
A Hub for Family and Friends: Lakes are natural gathering places. The calmer waters are perfect for teaching kids to swim, ski, or fish. Evenings are often spent around a bonfire, and the shared docks and community areas foster a strong sense of belonging among neighbors.
Versatile Four-Season Activities: Depending on the climate, lake life isn’t just for summer. Water skiing, tubing, and kayaking dominate the warm months. Autumn brings stunning foliage reflected on the water, perfect for tranquil canoe trips. In colder regions, the lake transforms into a winter playground for ice fishing, skating, and snowmobiling.
Calmer Waters and Environment: Freshwater is much gentler on your property and possessions than saltwater. Boats, docks, and lifts last longer with less maintenance. The environment is typically more sheltered from high winds and dramatic storms compared to the open ocean, providing a more tranquil atmosphere.
The Cons of Living on a Lake
Fluctuating Water Levels: Lake levels can change dramatically due to drought, seasonal rainfall, or dam controls. A severe drought could leave your dock high and dry, making boat access impossible. Conversely, heavy rains can lead to localized flooding.
Seasonal Population: Many lake communities are highly seasonal. They can be bustling with energy and activity in the summer but become very quiet, and sometimes isolated, in the off-season. This can be a pro for those seeking solitude but a con if you prefer a year-round vibrant community.
Bugs and Wildlife: Still or slow-moving freshwater is a breeding ground for insects, especially mosquitoes. You’ll need to factor in pest control measures like screened-in porches or professional spraying. You’ll also have more frequent encounters with local wildlife, which can be a charming perk or a nuisance depending on the species.
Riverfront homes offer a unique blend of dynamic scenery and convenient access to inland towns and cities.
Living on a river means witnessing a constantly changing landscape. The gentle flow, passing boats, and abundant wildlife provide a unique connection to nature that is both calming and ever-moving. Riverfront homes offer a distinct experience, blending seclusion with a sense of connection to the world flowing by.
The Pros of Living on a River
Ever-Changing Views: Unlike the static horizon of a lake or ocean, a river offers a dynamic panorama. The constant current, the seasonal shifts in foliage along the banks, the variety of birds and wildlife, and the occasional passing boat create a view that is never the same twice.
Boating and Fishing Paradise: A river is your highway to adventure. You can enjoy easy access for boating, often with the ability to travel from town to town or to larger bodies of water. Rivers are also prime spots for fishing, with different species inhabiting different parts of the current. Learning what you need to know about waterfront river homes is key to maximizing this lifestyle.
Greater Privacy and Natural Beauty: Riverfront lots are often larger, more wooded, and set further back from the water than their ocean or lake counterparts. This topography can offer a wonderful sense of privacy and seclusion, making you feel like you’re in your own private nature preserve.
The Cons of Living on a River
Flood Risk is a Major Concern: This is the single most significant challenge for riverfront property owners. Many homes are located in designated floodplains, making comprehensive flood insurance an absolute necessity. You must research the property’s flood history and elevation and be prepared for the possibility of evacuation during periods of heavy rain or spring snowmelt.
Currents and Debris: Strong river currents can pose a safety risk, especially for inexperienced swimmers. The flow can also carry logs, branches, and other debris downstream, which can damage docks, boats, and shorelines, requiring regular inspection and maintenance.
Bank Erosion and Stability: The river’s current is a powerful force that can gradually erode the bank of your property. Over time, this can threaten the stability of your land and any structures on it. Many homeowners must invest in costly stabilization measures like retaining walls or riprap to protect their property line.
Navigating the market for a waterfront property requires specialized knowledge and due diligence.
Buying a home on the water is more complex than a typical real estate transaction. As specialists in the field, we at homes-in-riverside.com guide our clients through the unique considerations to ensure they make a sound investment. The process involves much more than just appreciating the view; it requires a deep understanding of the environment.
Key Questions to Ask Yourself
What is my primary goal? Are you looking for a hub for family recreation, a place of quiet solitude, or an investment property for rental income? Your answer will point you toward a specific type of waterfront.
What is my budget for purchase and long-term maintenance? You must factor in not just the purchase price and closing costs, but also the ongoing costs of specialized insurance, potential seawall or bulkhead repairs, dock maintenance, and corrosion control.
How much privacy do I need? Consider the difference between a bustling public beach, a quiet community lake cove, and a secluded, wooded riverbank.
What activities are most important to me and my family? If you dream of surfing, the ocean is your only choice. If you love the idea of water skiing on calm water, a lake is ideal. If you’re an avid angler or kayaker who enjoys exploring, a river might be the perfect fit.
Understanding Regulations: A knowledgeable agent can help you navigate a maze of complex zoning laws, shoreline regulations (like the Clean Water Act), local building restrictions, and easements that can affect what you can do with your property.
Essential Inspections: We can connect you with inspectors who specialize in the unique features of waterfront homes, including docks, seawalls, bulkheads, boat lifts, and septic systems designed for waterside environments.
Assessing the Water Itself: An expert can help you research critical information that isn’t obvious at first glance, such as historical water quality reports, the property’s flood history, and any restrictions on navigational access or boat motor size for the specific property you’re considering.
Your Perfect Waterfront Awaits
Ultimately, the choice between an oceanfront, lakefront, or riverfront home is a deeply personal one. It’s about aligning the unique character of the water with the lifestyle you want to live. The vibrant energy of the ocean, the peaceful serenity of the lake, and the dynamic charm of the river each offer a distinct and wonderful way of life. By understanding the pros, cons, and responsibilities of each, you can move confidently toward making your waterfront dream a reality.
Frequently Asked Questions
What are the main lifestyle differences between living on the ocean, a lake, or a river?
The primary differences are in the environment and daily atmosphere. Oceanfront living is characterized by the sound of crashing waves, saltwater air, and expansive views. Lakefront living typically offers a calmer, more serene environment with still waters, ideal for quiet mornings. Riverfront living provides a sense of constant, gentle movement and a connection to a flowing ecosystem.
What types of activities are best suited for each waterfront location?
Each location caters to different recreational activities. Oceanfront properties are ideal for beach-going, surfing, and saltwater fishing. Lakefront homes are perfect for swimming, water skiing, kayaking, and leisurely boating in a more contained area. Riverfront living is excellent for canoeing, fishing, and enjoying the natural scenery and wildlife along the banks.
What are the key factors to consider when choosing a waterfront property?
Beyond the view, you should consider the lifestyle you desire, the types of activities you enjoy, and the specific maintenance requirements. Oceanfront homes face saltwater corrosion, lakefront properties deal with fluctuating water levels, and riverfront homes may have concerns about currents and flooding. Your choice should align with your budget, lifestyle preferences, and willingness to handle location-specific upkeep.
Is one type of waterfront property more expensive than another?
Costs can vary significantly based on location, but generally, oceanfront properties tend to have higher purchase prices and insurance costs due to demand and risk from storms. However, factors like property size, accessibility, and local market conditions heavily influence the cost for all types of waterfront homes, so it’s important to research specific areas.
Calculating the True Cost: A Seller’s Guide to Buyer Concessions in the Indianapolis Market
You’ve meticulously prepared your home, the listing photos look stunning, and after a busy weekend of showings, you have a fantastic offer in hand. The price is exactly what you hoped for, but as you read through the details, you see a catch—the buyer is asking for a $6,000 concession toward their closing costs. What does this actually mean for your bottom line? Is this a good deal or a financial trap?
Buyer concessions are a common but often misunderstood part of a real estate transaction in Indianapolis. While they can be a powerful tool to seal a deal, they can also significantly impact a seller’s net profit if not handled strategically. Understanding the true cost of these requests is the key to navigating your sale with confidence and protecting your hard-earned equity.
At homes-in-riverside.com, we are dedicated to empowering Indianapolis home sellers with the knowledge and expertise they need to navigate every aspect of their sale. This guide is designed to demystify buyer concessions, helping you calculate the true cost and make the best decision for your financial goals.
Key Takeaways
Buyer concessions are costs the seller agrees to pay on behalf of the buyer, most commonly for their closing costs or repairs.
The true cost of a concession is a direct, dollar-for-dollar reduction from your net proceeds, not just a negotiation tactic.
In the Indianapolis market, concession requests are heavily influenced by factors like current interest rates, the property’s condition, and the overall market temperature.
Evaluating an offer with concessions requires looking beyond the headline sale price to the strength of the buyer, their financing, and other contractual terms.
Partnering with an experienced local real estate agent is crucial for strategically negotiating concessions and protecting your equity.
TL;DR
Seller concessions are when you, the seller, agree to pay for some of the buyer’s expenses (like closing costs) to help make the deal happen. This directly reduces the cash you walk away with. For example, a $300,000 offer with a $5,000 concession nets you the same amount as a $295,000 offer with no concession. Understanding this simple calculation is the key to negotiating effectively in the Indianapolis real estate market.
What Are Buyer Concessions? A Plain-English Guide for Sellers
Before you can strategize, you need to understand exactly what you’re dealing with. A buyer concession isn’t just a simple price haggle; it’s a specific financial tool used in negotiations.
Defining the Term: More Than Just a Price Reduction
Many sellers mistakenly equate a concession with a price reduction, but they function differently and have distinct implications.
Seller Concession: A financial contribution from the seller to the buyer at closing. This money is credited to the buyer to be used for specific expenses, most often their closing costs. The sale price of the home remains the same on paper, but the seller’s net proceeds are reduced by the concession amount.
Price Reduction: A straightforward decrease in the home’s official purchase price. This lowers the amount the buyer needs to finance and can also affect other calculations, such as agent commissions.
The key difference is where the money comes from. A concession is a credit paid from the seller’s proceeds, while a price reduction lowers the total value of the transaction itself.
Common Types of Concessions in the Indianapolis Market
While buyers can theoretically ask for anything, concession requests in Indianapolis typically fall into a few common categories.
Closing Cost Credits: This is by far the most frequent request. A buyer asks the seller to contribute a specific dollar amount or percentage of the sale price to cover their closing costs. These costs can include loan origination fees, appraisal fees, title insurance, attorney fees, and prepaid property taxes. According to Freddie Mac, closing costs typically amount to (https://myhome.freddiemac.com/buying/what-are-closing-costs), which can be a significant financial hurdle for many buyers.
Repair Credits: After a home inspection reveals issues, a buyer might ask for a credit at closing instead of having the seller perform the repairs. This gives the buyer the flexibility to hire their own contractors and oversee the work after they take possession. For sellers, it can be a welcome alternative to the hassle of coordinating and paying for repairs before the closing date.
Home Warranty: A common and relatively low-cost concession is the seller agreeing to pay for a one-year home warranty policy for the buyer. This provides the new owner with peace of mind, knowing that potential issues with major systems (like the HVAC or plumbing) or appliances are covered for the first year.
Mortgage Rate Buydowns: A more sophisticated strategy involves the seller paying a lump sum to the buyer’s lender to “buy down” their mortgage interest rate. This can be a temporary buydown (e.g., reducing the rate for the first one or two years) or a permanent one. In a higher-interest-rate environment, this can be a very attractive incentive for buyers, as it lowers their monthly payment.
Why Buyers Ask for Concessions (It’s Not Always Personal)
When a buyer asks for a concession, it’s easy to feel like they’re trying to nickel-and-dime you. However, the request is usually driven by practical financial reasons or market dynamics, not a desire to undervalue your home.
Overcoming the Closing Cost Hurdle
The biggest driver of concession requests is cash. Many buyers, particularly first-time homebuyers, have diligently saved for a down payment but find themselves short on the additional liquid cash needed for closing costs. A seller concession allows them to roll these costs into their mortgage loan, making the purchase possible. By offering a concession, you can often enable a deal with a well-qualified buyer who might otherwise be unable to close.
Responding to Home Inspection Findings
The home inspection is a critical phase of any transaction. If it uncovers unexpected issues, such as a furnace nearing the end of its life or a need for minor electrical work, a concession can be the cleanest solution. Instead of a drawn-out negotiation over who will fix what, a simple repair credit can resolve the issue quickly and keep the transaction moving forward. It saves you, the seller, the time and effort of managing contractors while you’re trying to pack and move.
The Influence of the Indianapolis Market Climate
The prevalence of seller concessions is directly tied to the local market conditions. The balance of power between buyers and sellers dictates negotiation leverage.
In a Buyer’s Market: When there are more homes for sale than active buyers, sellers must compete for attention. In this scenario, offering concessions can be a proactive strategy to make your home stand out and attract strong offers.
In a Seller’s Market: When inventory is low and demand is high, sellers have the upper hand. Concessions become far less common, as buyers are competing against each other. However, even in a hot market, a concession can be a strategic tool to secure an otherwise perfect offer (e.g., one with a quick closing date or no other contingencies).
Currently, the Indianapolis market, like many across the country, is navigating the effects of fluctuating interest rates. This can increase the likelihood of concession requests as buyers look for ways to offset higher monthly payments.
The Main Event: Calculating the True Cost to Your Bottom Line
This is where the rubber meets the road. To make an informed decision, you must look past the offer price and calculate your estimated net proceeds.
The Simple Math: Sale Price vs. Your Net Proceeds
The formula to determine what you will actually walk away with is straightforward. It’s essential to remember that every single dollar you give in concessions is a dollar removed from your final profit.
Your Estimated Net Proceeds = Sale Price – Remaining Loan Payoff – Seller Closing Costs – Real Estate Agent Commissions – Buyer Concessions
Let’s break down this calculation with a real-world example common in the Indianapolis area.
A Real-World Indianapolis Seller’s Example
Imagine you’ve listed your Broad Ripple bungalow for $350,000. You receive two different offers on the same day. At first glance, one seems clearly better, but the math tells a different story.
Feature
Offer A
Offer B
Sale Price
$350,000
$355,000
Buyer Concession Request
$0
$6,000
Net Sale Price
$350,000
$349,000
Let’s analyze this:
Offer A: A clean, full-price offer at $350,000 with no concessions. After your other selling costs are paid, your profit is calculated based on this $350,000 figure.
Offer B: An offer for $5,000 over your asking price at $355,000. However, the buyer is asking for a $6,000 concession for their closing costs.
To find the true value of Offer B, you subtract the concession from the sale price:
$355,000 (Sale Price) – $6,000 (Concession) = $349,000 (Net Sale Price)
In this scenario, Offer A puts $1,000 more in your pocket than Offer B, despite having a lower sale price. This simple calculation is the most critical step in evaluating any offer that includes a concession request.
A Note on Appraisals and Concessions
There’s another potential pitfall with accepting a higher offer price to cover a concession, as seen in Offer B. The home must still appraise for the inflated purchase price of $355,000. If the appraiser determines the home’s fair market value is only $350,000, the lender will not approve a loan for the higher amount. This can lead to the deal falling apart or force you back to the negotiating table, potentially causing delays and costing you more in the long run.
Your Strategic Playbook for Handling Concession Requests
Receiving an offer with a concession request isn’t a “yes or no” question. It’s the beginning of a negotiation. A strategic approach can help you protect your investment while still achieving your goal of a successful sale.
Look at the Whole Picture, Not Just the Price
The best offer isn’t always the one with the highest net price. A savvy seller and their agent will evaluate the entire package:
Buyer’s Financial Strength: Is the buyer pre-approved with a reputable local lender, or do they have a less-reliable online pre-qualification? A larger down payment often signals a more financially stable buyer.
Contingencies: Are the inspection and financing contingency periods reasonable? An offer with fewer contingencies is stronger and less likely to fall through.
Closing Date: Does the proposed closing date align with your timeline? A quick, convenient closing can be worth thousands of dollars in saved carrying costs (mortgage, taxes, insurance).
An offer that nets you slightly less but comes from a rock-solid buyer with a quick closing date might be preferable to a marginally higher offer with more risks attached.
How to Negotiate: Counteroffers and Creative Solutions
You don’t have to simply accept or reject the buyer’s request. You have options:
Counter with a Partial Concession: If a buyer asks for $6,000, you can counter by offering to contribute $3,000. This shows you’re willing to work with them while still protecting your bottom line.
Offer a Repair Credit: If the request stems from inspection items, offering a credit is often better than doing the work yourself. It transfers the responsibility to the buyer and prevents any future disputes over the quality of the repairs.
Hold Firm: If you are in a strong seller’s market with multiple offers, you may have the leverage to reject the concession request entirely.
Your flexibility should depend on your motivation, your time on the market, and the overall strength of the offer. This is where understanding the new math of selling in Indy can be crucial for boosting your home equity.
The Value of High-Value Expertise in Negotiations
This complex analysis is where a true real estate professional proves their worth. An experienced agent from a service provider like homes-in-riverside.com doesn’t just forward offers to you. They act as your strategic advisor. They will prepare a detailed Seller’s Net Sheet for every offer, breaking down all the costs and showing you the precise, estimated amount you’ll receive at closing.
Furthermore, their deep knowledge of the Indianapolis market allows them to provide context. They can advise you on whether a concession request is reasonable for your neighborhood and price point, and they will use their negotiation skills to craft a counteroffer that achieves the best possible outcome for you. This expertise is what protects your equity and ensures you don’t leave money on the table.
Making a Confident and Profitable Decision
Navigating buyer concessions doesn’t have to be intimidating. By understanding that they are a direct cost against your profit, you can shift your focus from the headline sale price to the number that truly matters: your net proceeds. Evaluating every offer as a complete package—considering the buyer’s strength, the proposed terms, and the market climate—allows you to move from a position of uncertainty to one of empowered confidence.
The right guidance makes all the difference in a real estate transaction. A great agent helps you see the full financial picture, providing the strategic advice needed to handle any request that comes your way. This ensures you not only get your Indianapolis home sold but also maximize the return on your most significant investment.
Frequently Asked Questions
What is a buyer concession in a real estate transaction?
A buyer concession is an arrangement where the seller agrees to pay certain costs on behalf of the buyer. These costs are typically related to the buyer’s closing costs or for specific repairs requested after an inspection.
How does a buyer concession actually affect my profit as a seller?
A buyer concession is a direct, dollar-for-dollar reduction from your net proceeds. For example, if you agree to a $6,000 concession on a home sale, your final profit will be $6,000 less than it would have been without the concession.
Why would a seller agree to pay for a buyer’s costs?
Sellers often agree to concessions as a strategic tool to make a deal happen. It can help a buyer who is short on cash for closing costs, make an offer more attractive, or be a key negotiating point to secure a contract and close the sale successfully.
What are the most common things sellers pay for in a concession?
The most common costs covered by seller concessions are the buyer’s closing costs, which can include loan origination fees, appraisal fees, and title insurance. Another common concession is providing a credit to the buyer for specific repairs.
A Realtor’s Checklist: A Side-by-Side Comparison of Services Offered by 1% vs. 6% Agents
The Big Question for Home Sellers: Is a 1% Commission Too Good to Be True?
Introduction: Beyond the Commission Percentage
Selling your home is one of the most significant financial transactions of your life. It’s also one of the most expensive. When you see an advertisement for a 1% listing commission, the allure is undeniable. In a process filled with hefty costs, the thought of saving thousands, or even tens of thousands, on agent fees is powerful. But as with any major decision, the headline number rarely tells the whole story.
The core debate isn’t just about saving money on a fee; it’s about the total net profit that ends up in your pocket at the closing table. A lower commission is only a “win” if it doesn’t come at the cost of a lower sale price, a longer time on the market, or a deal that falls apart due to a lack of expert oversight. The value of true expertise is often found in the details—the strategic advice, the robust marketing, and the skilled negotiation that maximize your final outcome.
This post provides a clear, unbiased Realtor’s Checklist for a side-by-side comparison of the services offered by discount (1%) and traditional (6%) agents. Our goal is to empower you with the knowledge to look beyond the percentage and make an informed decision that best serves your financial interests.
Key Takeaways
Commission Isn’t Monolithic: A “6%” commission is typically split between the seller’s agent and the buyer’s agent, with each side’s brokerage receiving about 3%. This cooperative fee is crucial for attracting the largest pool of buyers.
Service Levels Vary Drastically: Full-service agents typically include comprehensive marketing, hands-on guidance, and expert negotiation as part of their commission. Discount models often offer a more basic service, with many critical tasks available only as à la carte add-ons for an extra fee.
Focus on Net Profit, Not Just Savings: A lower commission can be negated if the home sells for a lower price due to weak marketing or negotiation. The ultimate goal is to maximize your net proceeds after all expenses are paid.
Expertise Mitigates Risk: An experienced full-service agent acts as a project manager and problem-solver, navigating complex issues like inspections, appraisals, and buyer financing to ensure a smooth path to closing.
First, Let’s Demystify the “6%” Commission
Before we compare services, it’s essential to understand how real estate commissions actually work. The “6%” figure is a common benchmark, but it’s not what a single agent pockets. This commission is almost always split between the two parties representing the transaction.
Here’s a typical breakdown:
~3% for the Seller’s Agent’s Brokerage: This is the listing commission. From this, the agent pays their brokerage a split, covers all marketing expenses, and then takes their own income.
~3% for the Buyer’s Agent’s Brokerage: This is the “cooperative” or “co-op” commission. It’s the fee you, the seller, offer to the agent who brings a qualified buyer to purchase your home.
This buyer’s agent commission is one of the most powerful marketing tools at your disposal. By offering a competitive co-op fee, you incentivize thousands of local agents to show your property to their pre-qualified clients. Some discount models may reduce this co-op fee to 2% or 2.5% to make their total number look lower. However, this can be a critical mistake. In a competitive market, agents are more likely to prioritize showing homes that offer a standard commission, potentially reducing the number of eyes—and offers—on your property.
The Ultimate Side-by-Side Comparison Checklist
This is the heart of the matter. Let’s break down the home selling process into four key phases and compare the typical services you can expect from a 1% discount model versus a 6% full-service agent.
Phase 1: Pre-Listing Strategy & Home Preparation
The Goal: To price your home accurately and prepare it to attract the highest possible offers from day one.
Checklist Item
Typical 6% Full-Service Agent
Typical 1% Discount Agent
In-Depth Market Analysis & Pricing Strategy
Provides a comprehensive comparative market analysis (CMA) based on recent sales, pending sales, and active competition. Factors in hyper-local trends, property condition, and unique features. Includes a strategic pricing discussion to generate maximum interest and multiple offers.
Often relies on an automated valuation model (AVM) or a basic CMA with less nuance. The agent, handling higher volume, may have less time to dedicate to a deep dive into your specific property’s market position.
Staging & Presentation Advice
Offers a personalized, room-by-room staging consultation to highlight your home’s best features and appeal to the broadest buyer demographic. Often has a trusted network of professional stagers, cleaners, and handymen to recommend.
Typically provides a general advice pamphlet or a simple checklist. Hands-on staging coordination or professional referrals are often an add-on service for an extra fee.
Phase 2: Marketing & Property Exposure
The Goal: To reach the largest possible pool of qualified buyers with compelling, professional marketing that makes your home stand out.
Checklist Item
Typical 6% Full-Service Agent
Typical 1% Discount Agent
Professional Marketing Materials
Includes a full suite of professional marketing assets as part of the commission: high-resolution photography, cinematic videography, 3D virtual tours, and detailed floor plans. A professionally written property description highlights key selling points.
May use basic, agent-taken photos. Professional media is almost always an à la carte upgrade you must pay for out-of-pocket. The property description may be generic.
Comprehensive Marketing Campaign
Executes a multi-channel strategy: premium placement on the MLS, syndication to all major portals (Zillow, Realtor.com), targeted social media advertising campaigns, email blasts to an extensive agent network, and potentially print ads or high-quality brochures.
Provides a basic MLS listing and standard syndication to major portals. Proactive marketing efforts like social media campaigns or agent outreach are usually minimal or non-existent.
Showings & Open Houses
Personally hosts open houses to engage with potential buyers and answer questions in real-time. Coordinates and often attends private showings to highlight features that might be missed and gather immediate, valuable feedback.
May use a third-party call center for scheduling showings. Relies on lockbox access for buyer agents to show the home unassisted. Hosting an open house is often an additional charge.
Phase 3: Offer Negotiation & Vetting
The Goal: To secure the best possible price and terms while minimizing your risk. This is often where an expert agent provides the most significant value.
Checklist Item
Typical 6% Full-Service Agent
Typical 1% Discount Agent
Expert Negotiation
Leverages deep experience to negotiate not just the price, but also critical contingencies (inspection, appraisal, financing), closing dates, and other terms that protect you. Expertly manages multiple-offer scenarios to create a bidding war and drive the price higher.
May have less hands-on negotiation experience or follow a standardized, less-flexible approach. With a high volume of clients, the agent has limited time to dedicate to the nuances of your specific negotiation, potentially leaving money on the table.
Buyer Qualification
Thoroughly vets potential buyers beyond the pre-approval letter. This includes speaking directly with the buyer’s lender to confirm their financial strength, understanding the status of their loan, and reducing the risk of a deal falling through weeks before closing.
Often relies solely on the pre-approval letter provided by the buyer’s agent. There is typically less proactive vetting, which can increase the risk of the transaction failing due to financing issues.
Phase 4: Transaction Management & Closing
The Goal: To navigate the complex escrow process smoothly and ensure a successful, on-time closing.
Checklist Item
Typical 6% Full-Service Agent
Typical 1% Discount Agent
Hands-On Problem Solving
Acts as your dedicated project manager. They proactively coordinate with inspectors, appraisers, title companies, and the other agent. They are your first line of defense, skillfully navigating and resolving common issues like low appraisals or inspection repair requests.
Functions more as a coordinator than a problem-solver. You may be responsible for more of the legwork and communication. Support for complex issues may be limited or passed to a transaction coordinator with whom you have no prior relationship.
Agent Availability & Communication
Serves as your single, dedicated point of contact from start to finish. Provides regular, proactive updates and is readily available to answer your calls, texts, and emails, offering peace of mind throughout the process.
You may be dealing with a team-based model or a call center, meaning you speak with a different person each time you have a question. This can lead to less personalized, one-on-one attention from a single agent who knows every detail of your sale.
The Real Bottom Line: Net Profit vs. Commission Savings
After reviewing the checklist, it’s clear that the services offered are fundamentally different. The choice isn’t between two identical services at different prices; it’s between a full-service, comprehensive management model and a more limited, à la carte model.
This is where you must ask the critical questions:
Could superior marketing, staging advice, and professional photography from a 6% agent result in a sale price that is 3-5% higher? If so, that difference alone could more than cover the additional commission.
What is the financial risk of a deal falling apart? According to the National Association of REALTORS®, 5% of contracts were terminated in the three months leading up to March 2024. An experienced agent’s ability to vet buyers and solve problems during escrow significantly mitigates this risk.
What is the cost of your own time and stress in managing more of the process, coordinating with vendors, and handling issues with a less-involved agent?
The unique value proposition of a full-service agent isn’t just in the tasks they perform, but in the expertise, risk mitigation, and financial optimization they bring to the table. Their goal is aligned with yours: to secure the highest possible net proceeds from your home sale.
Your Next Step: Get a Clear Picture of Your Home’s Value
Choosing a real estate agent is one of the most important financial decisions you will make. Don’t let the commission percentage be the only factor. Use this Realtor’s Checklist to interview potential agents and evaluate the full scope of services offered and the tangible value they provide. The right agent doesn’t cost you money; they make you money by maximizing your home’s value on the open market.
Ready to see what high-value expertise can mean for your home sale? Contact us for a no-obligation, comprehensive home valuation and a personalized marketing plan. We’ll show you exactly how we work to maximize your net proceeds and deliver a seamless selling experience. You can also browse our current listings to see our marketing in action.
Frequently Asked Questions
What is the primary difference between a 1% and a 6% real estate agent?
The main difference lies in the commission fee and the scope of services offered. A 1% agent charges a lower fee, while a traditional 6% agent typically provides a more comprehensive service package, including robust marketing, strategic advice, and skilled negotiation, aimed at maximizing the seller’s final net profit.
Is choosing a 1% commission agent always the best way to save money when selling a house?
Not necessarily. While the upfront commission is lower, the true financial outcome depends on the final sale price. The article suggests that a lower commission could come at the cost of a lower sale price or a deal falling apart due to a lack of expert oversight, potentially reducing your total net profit.
What is the main argument for choosing a traditional 6% agent over a 1% discount agent?
The main argument is the value of expertise. A traditional agent’s higher commission is justified by their potential to secure a higher sale price through strategic advice, comprehensive marketing, and expert negotiation, ultimately maximizing the seller’s net proceeds from the sale.
How is a traditional 6% real estate commission typically split?
A ‘6%’ commission is generally not paid to a single agent. It is typically split between the seller’s agent and the buyer’s agent to compensate both for their work in the transaction.
In the competitive Southern California real estate market, homeowners are constantly looking for ways to make their properties stand out. While aesthetic updates like a new kitchen or a bathroom remodel are popular, a new wave of home improvements is proving to be even more valuable: eco-friendly upgrades. These green enhancements not only increase your property’s market appeal but also save you a significant amount on utility bills. For Riverside homeowners, investing in sustainability is a savvy financial decision that pays dividends both now and when it’s time to sell.
This guide explores the most impactful eco-friendly upgrades that offer the best return on investment, making your home more comfortable, affordable, and attractive to future buyers.
Why Go Green? The Dual Benefits for Homeowners
Choosing to implement eco-friendly upgrades is a win-win scenario. The benefits extend far beyond simply reducing your carbon footprint; they have a tangible impact on your finances and quality of life.
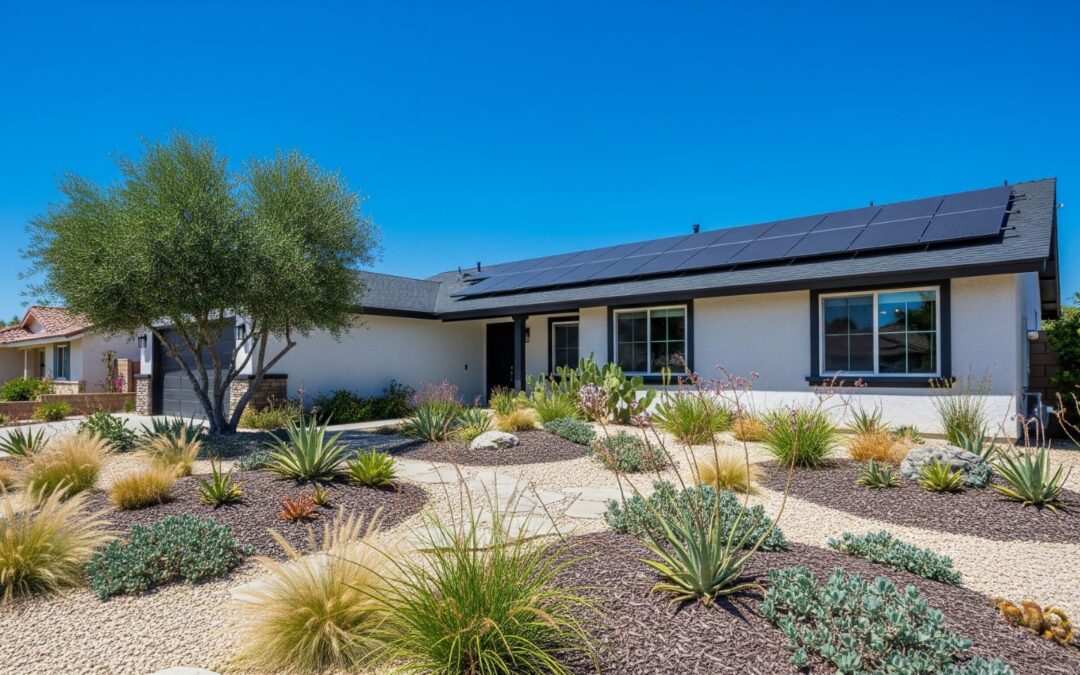
First, the most immediate advantage is the reduction in monthly utility costs. A well-insulated home with energy-efficient appliances and windows requires less power to heat and cool. In a climate like Riverside’s, where summer air conditioning bills can be substantial, these savings add up quickly. Similarly, water-wise landscaping can dramatically lower your water bill, a crucial benefit in a region prone to drought.
Second, green homes are increasingly in demand. Modern buyers are more environmentally conscious and knowledgeable than ever before. They recognize that a home with features like solar panels or superior insulation will be cheaper to run long-term. This makes your property more appealing, potentially leading to a faster sale and a higher selling price. Appraisers are also beginning to assign higher values to homes with certified green features, solidifying their status as a wise investment.
High-Impact Upgrades for a Greener Home
Not all green upgrades are created equal. To get the most value for your money, focus on improvements that deliver the biggest impact on energy consumption and curb appeal.
Upgrade Your Insulation: The Unseen Hero of Energy Efficiency
Before you even think about solar panels or smart gadgets, look at your home’s insulation. It’s the single most critical factor in regulating your home’s temperature. Many older homes in the Riverside area are under-insulated, leading to massive energy loss through the attic and walls. Upgrading your insulation creates a stronger thermal barrier, keeping your home cooler in the summer and warmer in the winter without constantly running your HVAC system.
There are various types of insulation, from traditional fiberglass batts to modern spray foam. Understanding the way spray foam insulation works, for example, reveals how it can create an airtight seal that blocks heat transfer far more effectively than other materials. This single upgrade can reduce your heating and cooling costs by up to 20%, making it a foundational and highly effective green investment.
Install Energy-Efficient Windows
Your windows are another major source of energy loss. Old, single-pane windows do little to stop the transfer of heat. Replacing them with modern double-pane or even triple-pane windows with Low-E (low-emissivity) coatings can make a world of difference. These windows reflect infrared light, keeping heat out during the summer and in during the winter. Not only do they improve energy efficiency, but they also reduce outside noise and protect your furniture and flooring from fading due to UV rays. While the upfront cost can be significant, the energy savings and added home value make it a worthwhile project.
Embrace Solar Power
With over 270 sunny days a year, Riverside is an ideal location for solar energy. Installing solar panels on your roof allows you to generate your own clean electricity, drastically reducing or even eliminating your dependence on the grid. The long-term savings can be immense, and various federal and state incentives can help offset the initial installation cost.
Homes with paid-off solar panel systems are incredibly attractive to buyers who are eager to enjoy the benefits of low electricity bills from day one. It’s a clear, marketable feature that sets your home apart and justifies a higher asking price.
Smart Thermostats and Appliances
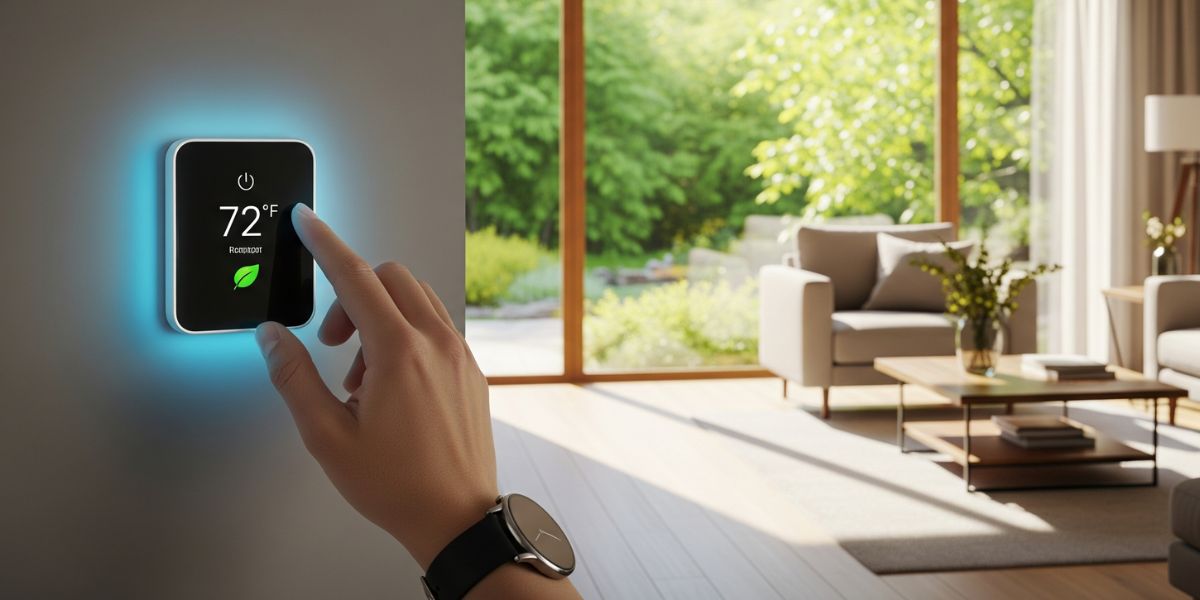
Technology offers simple yet powerful ways to make your home greener. A smart thermostat, for instance, learns your daily routines and automatically adjusts the temperature for optimal comfort and energy savings. You can control it from your smartphone, ensuring you’re not wasting energy cooling an empty house.
When it’s time to replace old appliances like your refrigerator, dishwasher, or water heater, look for models with the ENERGY STAR label. These products are certified to use significantly less energy and water than standard models. Homeowners can find a wealth of information and certified products on the official ENERGY STAR website.
Navigating the Financials of Green Upgrades
Investing in your home’s future is a smart move, but it’s important to plan for the costs. Financing these upgrades can be approached in several ways, from home equity loans to specific “green” financing programs. Furthermore, some of these improvements can positively impact other areas of homeownership. For instance, fortifying your home with new windows or a new roof as part of a green upgrade can be one of the many things that can lower your homeowner’s insurance.
When planning your budget for these projects, it’s helpful to think of them as part of the overall financial picture of homeownership. Just as you plan for understanding closing costs when buying your new home, you should also budget for valuable long-term improvements that enhance its value and reduce running costs.
Deciding which upgrades will provide the best return in the local market can be complex. This is where finding the right agent who understands the local market becomes invaluable. An experienced real estate professional can guide you on which green features are most sought-after by Riverside buyers, ensuring your investment directly translates to a higher resale value.
A Smart Investment for a Brighter Future
Making eco-friendly upgrades to your Riverside home is more than just a trend; it’s a strategic investment in your property’s future. These improvements offer the rare dual benefit of reducing your monthly expenses while significantly increasing your home’s marketability and value. From the foundational strength of proper insulation to the modern appeal of solar panels, going green is the smartest way to build a more comfortable, sustainable, and profitable home.
There are many benefits to using a realtor. From getting the best deal, to staying on the right side of the law. It is stressful to buy and sell a house. Showings. Listings. Open houses. Taxes. Closing costs. Paperwork or paperwork. And that’s just to name a few.
It’s tempting to believe that you can do it all on your own, especially with the wealth of information available online (and through Property Brothers!) Real estate transactions are time-consuming, complicated and can cost you money if they are not handled correctly.
It’s not in your interest to represent yourself if you are buying or selling a house. A Realtor is the best person to help you with your real estate needs.
Here are a few compelling reasons (and ones that will save your sanity) to hire a Realtor.
1. Realtors adhere to a code of conduct
Although we think most real estate agents are honest, members of the National Association of Realtors have agreed to follow the Realtor Code of Ethics. This code contains 17 rules to ensure that standards of conduct to promote fairness and honesty are met.
This means that your Realtor will only be looking for you. It’s that simple.
2. Insiders have access to information
Every industry has its own language, vast network system and trade secrets. Real estate is no exception. When an agent gets a real estate license, they get all that information.
Realtors are constantly in touch with other professionals and gain exclusive market data from the National Realtors Association. This helps them stay on top of what’s going on in the housing industry. Realtors know about the hottest subdivisions, the newest blocks and how to get the best deals for their clients.
Real estate agents are familiar with CMAs, EIKs, and FSBOs. Amortizations, appraisals, and assessments. Cash reserves, collateral and co-mingling. Consider getting an agent to translate if you do not understand the lingo.
The majority of homes are sold through networking, not advertising.
You can access the extensive list of contacts that a realtor has, including friends, family members and past clients. Your Realtor may know another Realtor that knows a family who is looking for what you are selling or selling what you want.
These relationships can help you to get the most accurate representation of the property and the best price for the sale, whether you are buying or selling.
3. They are marketing experts…
Realtors are experts at staging homes for showings, planning the perfect open houses and photographing properties in the best light possible for listings.
We know that you have good taste, and that HGTV taught you a few things about selling a house. We know that you are busy with a job, family and other responsibilities. You can let an expert handle your real-estate venture.
According to a survey conducted by the National Association of Realtors in 2017, 30 percent of home buyers found their homes with the assistance of an agent, and 51 percent did so on the Internet.
The NAR gives Realtors the most up-to-date marketing strategies. The Realtors network via Facebook groups, NextDoor, and LinkedIn in order to reach more buyers and sellers.
As a homeowner you can only share a listing with your friends on Facebook so many times before they ignore it for 30 days.
4. Negotiators who are tough
The final price is what matters, and the idea that an agent will get a portion of it can be unsettling for some sellers.
According to NAR statistics from 2016, the average price of a home sold by an owner was $208,700, compared to $235,000 in a sale with an agent. This shows that you are more likely than not to get the price you desire (and perhaps even more) when you work with a professional.
A bigger profit will still allow you to walk away with all the money you wanted.
Plus, realtors don’t have an emotional attachment to your home. It’s good that you are emotionally invested in your home, as most likely, it is. It’s hard to let go of the memories that are ingrained in your home, both good and bad.
People simply do not make the best choices when they are emotional. A Realtor is a constant with common sense who uses his head to negotiate instead of his emotions.
5. Realtors help you stay on the right side of the law
Do you need to inform a prospective seller of that water leak which you never repaired? You should test the paint of your older house for lead before you put it on sale. Do you have any restrictions in the deeds of the property that you are hoping to purchase? What is Dodd Frank?
You will have dozens of questions when buying or selling a house that you won’t be able to answer quickly with an internet search. Finding a Realtor can be of great help in this situation.
Realtors are always up to date with ever-changing laws and regulations that govern property sales, and you don’t need to be. This is thanks to the National Association of Realtors, and state Realtors associations.
FSBO is an abbreviation that stands for “for sale by owner.” This is the term commonly used to describe properties that are being advertised and sold directly to the public, as opposed to a real estate agent or a property developer marketing it.
Selling a home FSBO is not only a great way to save on commission fees but can also be quite beneficial if you have another home that you can move into while selling your current residence. FSBO stands for For Sale By Owner, which means that you will not have the assistance of a real estate agent when attempting to sell your home.
If you are thinking about selling your home this way, there are some things that you should know first.
What are the benefits of selling your home FSBO?
If you are looking to sell your home quickly and for a good price, then putting it up for sale by owner may be a good option for you. The main benefit of selling your home FSBO is that you will not have to pay any commission fees to an agent.
If you are selling a particularly expensive home, this can amount to a large amount of money, so it is certainly worth considering. Another benefit is that you will be able to control the entire process of the sale.
You will be in the driver’s seat when it comes to showing your home and answering any questions that potential buyers may have. You can take as long as you want to make a decision, and you won’t be pressured by a real estate agent.
Drawbacks of selling a home FSBO
Although selling your home FSBO can save you a lot of money in commission fees, it also means that you will have to handle everything on your own. You will have to advertise your home, show it to potential buyers, and work with them to get them to the point where they are ready to make an offer.
You will also have to be ready to handle any issues that may arise with the sale and any inspections that may be necessary. When you sell a home with a real estate agent, they will handle all of these things for you. Another drawback is that you will not have access to the same amount of potential buyers when selling your home FSBO.
When you list your home with a real estate agent, they will be able to list it on multiple websites, but when you try to sell it yourself, you will be limited to ads in the local paper or online sources. When you put your home up for sale by owner, you are also putting yourself at risk of getting scammed.
Because you will be dealing directly with potential buyers, you will not have the protection that real estate agents provide in terms of verifying their identity and financial ability to purchase the home. You will have to be very careful when it comes to accepting offers and making sure that you are working with legitimate people.
You will also have to deal with all of the paperwork related to the sale of your home yourself. This can be a very time-consuming process, especially if your home takes a long time to sell.
Before you put your home up for sale by owner
Before you decide to sell your home FSBO, it is important to be realistic about the amount of time it will take to sell. Selling a home can be a lengthy process, and you don’t want to be in a hurry to get rid of it. It is also a good idea to make sure that your home is presentable and in good condition before putting it up for sale.
This will help you sell it quicker and for more money. Before you put your home up for sale by owner, you should take care of any repairs that need to be made and clean it thoroughly. You should also hire a professional to look over your home and give you their opinion on how much it is worth. This will help you know what price to put on your home when potential buyers come to look at it.
Things to keep in mind when selling FSBO
If you are planning to sell your home FSBO, there are a few things that you should keep in mind before starting the process. You will need to thoroughly clean your home and make sure that everything is in good condition. You will also want to create attractive ads and be ready to answer any questions that potential buyers may have.
You should have a plan of action when it comes to advertising your home. This will help you get the word out about it as quickly as possible. You should also consider hiring a real estate agent to act as your agent. Many agents are willing to do this for a small fee and will be able to get your home listed on more websites than you would be able to do on your own.
When you are selling a home FSBO, it is important to be patient and never give up. You will likely encounter some roadblocks along the way, and there will probably be some times when you wonder why you ever decided to try to sell your home this way. If you keep plugging away, though, you will be successful in the end. Make sure that you are ready for the challenge before you make the decision to sell your home FSBO.
How to price your house before putting it up for sale by owner
Before you even begin to think about putting your home up for sale, you will need to come up with a price for it. The price of your home will be the single biggest factor in determining how long it takes to sell and for how much money.
There are many different methods that people use to come up with the price of their home when selling it FSBO. Some people choose to use the formula of the price per square foot of their home multiplied by the number of bedrooms and bathrooms. Other people choose to base the price on the amount of their mortgage plus the expenses that they have each month related to owning a home.
No matter which method you choose to determine the price of your home, there are a few things that you need to keep in mind. First, you should make sure that the price of your home is high enough to cover the expenses that you will have while selling it.
This includes things like homeowner’s insurance, property taxes, maintenance, and interest on your mortgage. You also need to make sure that the price is low enough to encourage people to buy it. If you price your home too high, it may not sell at all. Once you have decided on the price of your home, you can begin advertising it and accepting offers.
Conclusion
So, is it a good idea to sell your home on your own? The answer is you will first need to decide whether or not your home is a good candidate for this type of sale. Selling a home FSBO is usually best for people who have a home that doesn’t have much equity or for those who don’t want to pay a real estate agent to sell their home.
The advantages of selling a home FSBO are that you will not have to pay commission fees, you will be able to control the sale, and the process is usually a bit quicker.
The drawbacks are that you will have to handle all of the legwork when selling your home and you run the risk of getting scammed.
Before you decide to sell your home FSBO, it is important to be realistic about how long it will take to sell and to make sure that it is presentable. You will also need to come up with a price for your home before you can begin advertising it.
Although it will take time, this could help you save a lot of money on homeowners insurance. Ask your friends, consult Google, or contact your state’s insurance department. The National Association of Insurance Commissioners, can help you find an insurer in your state. Many states make it easy to find information about the rates charged by major insurance companies and provide data on complaints received by consumers.
You can also check out consumer guides, online insurance quote sites, and insurance agents. These will provide you with an overview of the price ranges and help you determine which companies offer the best prices. Don’t just focus on the price. You should find a reasonable price for the insurance company you choose and provide the same quality services that you would expect to receive if you need assistance with filing a claim.
Check the financial stability of the companies you are considering. Once you have narrowed down the field to three insurance companies, request price quotes.
Raise the Deductible
According to your policy, deductibles are the amount you must pay towards a loss before your insurer starts paying a claim. Your deductible will affect how much you can save on your premiums.
Most insurance companies recommend that you have a minimum $500 deductible. You can save up to 25% if you raise your deductible to $1,000. Keep in mind that your insurance policy may include a separate deductible for disasters if you live near one.
Depending on where you live there may be various deductibles, such as hail, high winds, or earthquakes.
Do Not Add Land Value
Your land beneath your home is not at risk of theft, windstorm, fire, and other perils. It is not worth any homeowners insurance. You will end up paying a higher premium if you do and it will not affect you later if you decide to sell your home.
Bundle Your Home & Auto Policies
If you purchase multiple policies from the same company that sells homeowners, auto, and liability coverage, they may offer a discount of 5 to 15% on your premium. However, this price should be lower than purchasing different coverage from different companies.
Make Your Home More Resilient
Ask your realtor, insurance agent, or representative at the company what you can do to make your home more resilient to windstorms. You might be able to reduce your premiums by installing storm shutters, strengthening your roof, or updating your roof with stronger materials like Slate, concrete, and clay roofing tiles
Retrofitting older homes can make them more resilient to earthquakes. To reduce fire and water damage, you should also modernize your heating, plumbing, and electrical systems.
Make Your Home More Secure
Smoke detectors, burglar alarms, and deadbolt locks are usually eligible for discounts up to 5 percent. If you have a sophisticated sprinkler system, a fire/burglar alarm that automatically ring the police and/or fire stations, some companies will offer discounts up to 15-20 percent.
These systems can be expensive and not all systems qualify for a discount. Find out which type of system your insurer recommends and what the cost would be. Also, learn how much you can save on your premiums.
You Might Be Eligible For Other Discounts
There are many discounts offered by companies, but not all of them offer the same discount.
Retired people are less likely to be burglarized than those who work. They may also spot fires earlier, as they tend to stay home longer than their counterparts. Retired persons also have more time to maintain their homes. Retired people over 55 may be eligible for discounts up to 10% with some companies.
Group insurance may be offered by some employers or professional associations that offer better deals than what you might find elsewhere.
Keep a Clean Credit History
A solid credit history is a great way to reduce your insurance costs. Credit information is increasingly being used by insurers to price homeowners’ insurance policies. Your insurer must inform you of any adverse actions, such as a higher interest rate. You should then verify the accuracy of the information the insurer relied on.
Pay your bills on time to protect your credit rating. Don’t get more credit than you really need. Keep your credit card balances low. You should regularly review your credit report and correct any errors promptly to ensure that it remains accurate.
Keep the Same Insurance Company
You may be eligible for a discount if you have been a long-term customer of a company. If you are a policyholder for more than six years, some insurers will reduce your premiums by 5% to 5%. However, it is important to compare the price of your policy with other policies.
At least once per year, review your policy limits and the value of your possessions.
The question of how much it costs to sell a house often comes up for sellers and potential buyers alike. This is one of the most fundamental questions that every buyer and seller should ask themselves. Knowing the cost of selling a home will not only help you determine if the asking price is reasonable, but it will also give you a better idea of how much you should really be asking for the property. Understanding how real estate commission works and understanding closing costs could help you determine whether or not selling your house will be profitable.
Real Estate Commissions
Selling a home costs about 10% of the home selling price. A real estate agent gets paid a commission for every house they sell. This commission varies from one real estate agent to the next, but typically the commission is in the neighborhood of five to six percent of the selling price. This six to seven percent figure is just one component of the many fees that must be paid by the buyer who wishes to sell. These fees include a real estate agent’s commission, closing costs, buyer’s association fee, listing and title fees, a discount real estate broker‘s commission, property assessment fee, and the real estate commission.
Why Are Real Estate Commissions So High?
One reason is that real estate commissions are based on the average sale price of comparable homes in the area. Another reason is that real estate commissions are paid once, whereas mortgages and buyers’ loans often need to be paid back several times over the course of a home’s lifetime. Many buyers do not understand what is involved in the process of paying back their mortgage or buying their first house. In addition, real estate commissions can be subject to change, since they are negotiated at the time of the sale rather than at the time of the contract.
Does the Location of the Home Impact Selling Costs?
The location of your home will greatly impact how much it costs to sell your home. Homes located in nicer neighborhoods tend to be more expensive to sell than homes in more remote areas, because there is more competition for buyers. In more remote areas, it may take more time for potential homebuyers to find a home, which could lead to higher closing costs and less money from the sale. So you will likely see a larger home closer to the city, with higher real estate fees, and a smaller, more rural home closer to the farm or the nearest town.
The Marketing Process Matters When You Sell a House
The amount of time spent on the marketing process is another important factor. Realtors take into account marketing efforts when calculating the cost of listing houses. This includes looking for good buyers, preparing marketing materials, finding out about local real estate market trends, preparing for open houses, advertising and participating in open houses, and following real estate market trends to make the most of real estate sales. In addition to how much does it cost to list a home, buyers and sellers must also determine if they will enter into the escrow process after the closing process has been completed.
What Other Fees Can Be Included When You Sell a House?
You have to consider all aspects of your home’s appearance before you make any decisions about your home. Include the cost of landscaping and improvements, like mowing the lawn and painting the house. These costs will add up quickly, and you have to know what you are talking about when you are talking about these costs. Also include the cost of real estate fees, which can often be expensive if you have not saved up enough money on your mortgage balance to cover them. Your closing costs, which include appraisals, insurance, and title insurance, will also need to be considered.
What Are Closing Costs?
Closing costs are the portion of a sale that is subtracted from the final sale price in order to pay for realtor fees, property taxes, and other miscellaneous items that sellers usually include in the purchase price. Closing costs can vary greatly depending on the type of property in question, as well as the market for properties in the area. Also, the size of the property can affect the amount that is paid out in closing costs.
Conclusion
The cost of buying a property can be very difficult to determine without a clear picture of all of the costs that are associated with taking possession of the property and transferring ownership. When you decide to put your house on the market you will need to understand how much it will cost to raise the asking price, how much it will cost to list the property on the MLS listing, and how much it will cost to perform the various tasks associated with selling a property. Once you have a clear picture of these costs, you will be in a better position to negotiate a realistic price with your realtor.
The phrase “discount real estate broker” generally refers to an individual or company that offers commission savings on property sales. These brokers often offer discounts to both homebuyers and sellers alike for residential, commercial, and industrial properties. Some discount real estate brokers even offer rebate or bonus incentives at closing for when you buy a home or when you sell your home. These brokers have access to resources that would normally be unavailable to homebuyers and sellers, and they make offers on properties that would not normally be offered to them by traditional realtors.
Discount Real Estate Brokers Are a Bridge
One of the reasons that brokers are able to offer such substantial discounts is due to the fact that brokers are often hired as a bridge between a seller and buyer. In many instances, a full service broker can take the position of a buyer’s agent while the seller acts as the seller’s agent. While a typical listing agent makes an offer on a property, a full service sales experience allows the seller to make an offer with their own agent, with less money out of pocket. This gives the seller the ability to make a counteroffer, should the counter offer be turned down. If the offer made by the listing agent is matched by the seller, the listing agent makes money off the full service commission.
Discount Real Estate Brokers Understand Market Trends
Full service brokers have the benefit of knowing market trends and buying trends, which allows them to make wiser offers on property. These brokers have the benefit of working with buyers and sellers from across the country and they have access to multiple listing services, with discounted prices on homes from every part of the country. Discount brokers do not typically work with full buyer or seller pools, so they are typically more cost effective for people looking to save money.
Discount Real Estate Brokers Are Assets For Investors
For any real estate investor, a discount real estate broker can be an invaluable asset. When you are buying or selling a home, you want to get the best bang for your buck. A discount real estate broker can work at a lower rate, but if they don’t offer even the most basic service, they get to earn that big fat dip in profit by simply increasing their number of clients. The more clients that they serve, the less time they need to spend working on you. This is how they stay in business. Typically full-service brokerage firms will offer discounts to attract new business and are willing to negotiate closing costs. Some discount brokers offer discounts on their commission structure to retain existing clients. Such commission structures may include flat rate reductions for new sales and special incentives for renewing or remodeling contracts.
However, not every discount real estate broker offers this kind of thing. What we want from the right real estate agent is someone who will work with us until we are ready to buy or sell a home. Someone who will help us through every step of the selling process – from initial contact right down to the filing of all of the necessary paperwork and the final sale of the home. But the one model that every home seller should be using when they are selling their home is the flat fee MLS.
Conclusion
Flat fee MLS listing services are offered by virtually every discount real estate broker today. If you want to sell your home fast, you should use these services. You can save money and use a marketing strategy that works. And you can rest assured knowing that you are not being cheated by a commission hungry seller. A real estate listing service is a powerful tool that can give you the upper hand in the selling game!
It is a seller’s market so if you’re ready to sell your home, 2019 is the year to move forward with your plans. It’s been several years since the real estate market made any big changes and many think one is overdue. Nowadays, more buyers exist than homes for sale to the point to where investors are buying homes in Mexico.
Selling a home this year can produce an easier buying process and better profits – all the things that make home seller’s happy. It is easy to sell a home in a seller’s market, but don’t assume that the property will sell itself. To ensure maximum profit and a smooth closing day, there are a few steps that you should take when selling a home.
The Price is Right
Buyers assume the price they see for a home is the price they pay. They don’t think of sellers as being the best negotiators. As home prices are changing across the country, getting the price from the start is very important. Because there is truth to the relationship between time and money. Overpricing a home can often cause it to sit on the market much longer as buyers move onto newer and fresher inventory.
A buyer wants to endure as few headaches as possible during the process, just like you want things to go smoothly. In the end, you’ll likely need to cut the price to sell it anyway, so why not minimize the headache from the start? So, don’t think of the ‘come down in price later’ strategy works and price the home competitively from the start.
You Got The Look
No matter how new the home, buyer’s will look right past the property if it is not staged. Buyer’s want a home that is appealing; that feels like home to them. Strategic staging will help potential buyers better envision the property as a home, as their home, so it will sell much faster. Giving potential buyers that boost of imagination they need will certainly pay off when the day is done.
First Impressions Matter
Don’t forget the outside of the property when staging it to sell. It’s the first thing that a potential buyer sees when they arrive at the home. If they’re met with an unkempt lawn, dead, brown grass, peeling paint, or junk sitting outside, they’ll think twice about even going inside the home. Make sure that first impression counts. It doesn’t take a lot of money or hard work to create a space that dramatically enhances the appeal of the home, so don’t be shy about completing these steps.
Hire A Real Estate Agent
You need a real estate agent there to help with every step of the selling process. Don’t assume that an agent is helpful only when you plan to buy a home. They’re essential to a smooth selling process, too. Agents know the housing market, how to price a home, how to intrigue an audience and potential buyers, and how to make the seller happy. Do your homework when it’s time to choose an agent. There’s plenty of information waiting to learn if you aren’t afraid to do your research.